What’s your biggest monthly expense? If you’re renting, it’s probably your rent.
Did you know you can pay your rent on time every month for years, and it still might not show up on your credit history? That can be frustrating, especially if you’re hoping to buy a home someday and are working to build your credit.
The good news is that things are starting to change. Here’s what you need to know and how it could help you get one step closer to owning a home.
The Problem for Would-Be Buyers
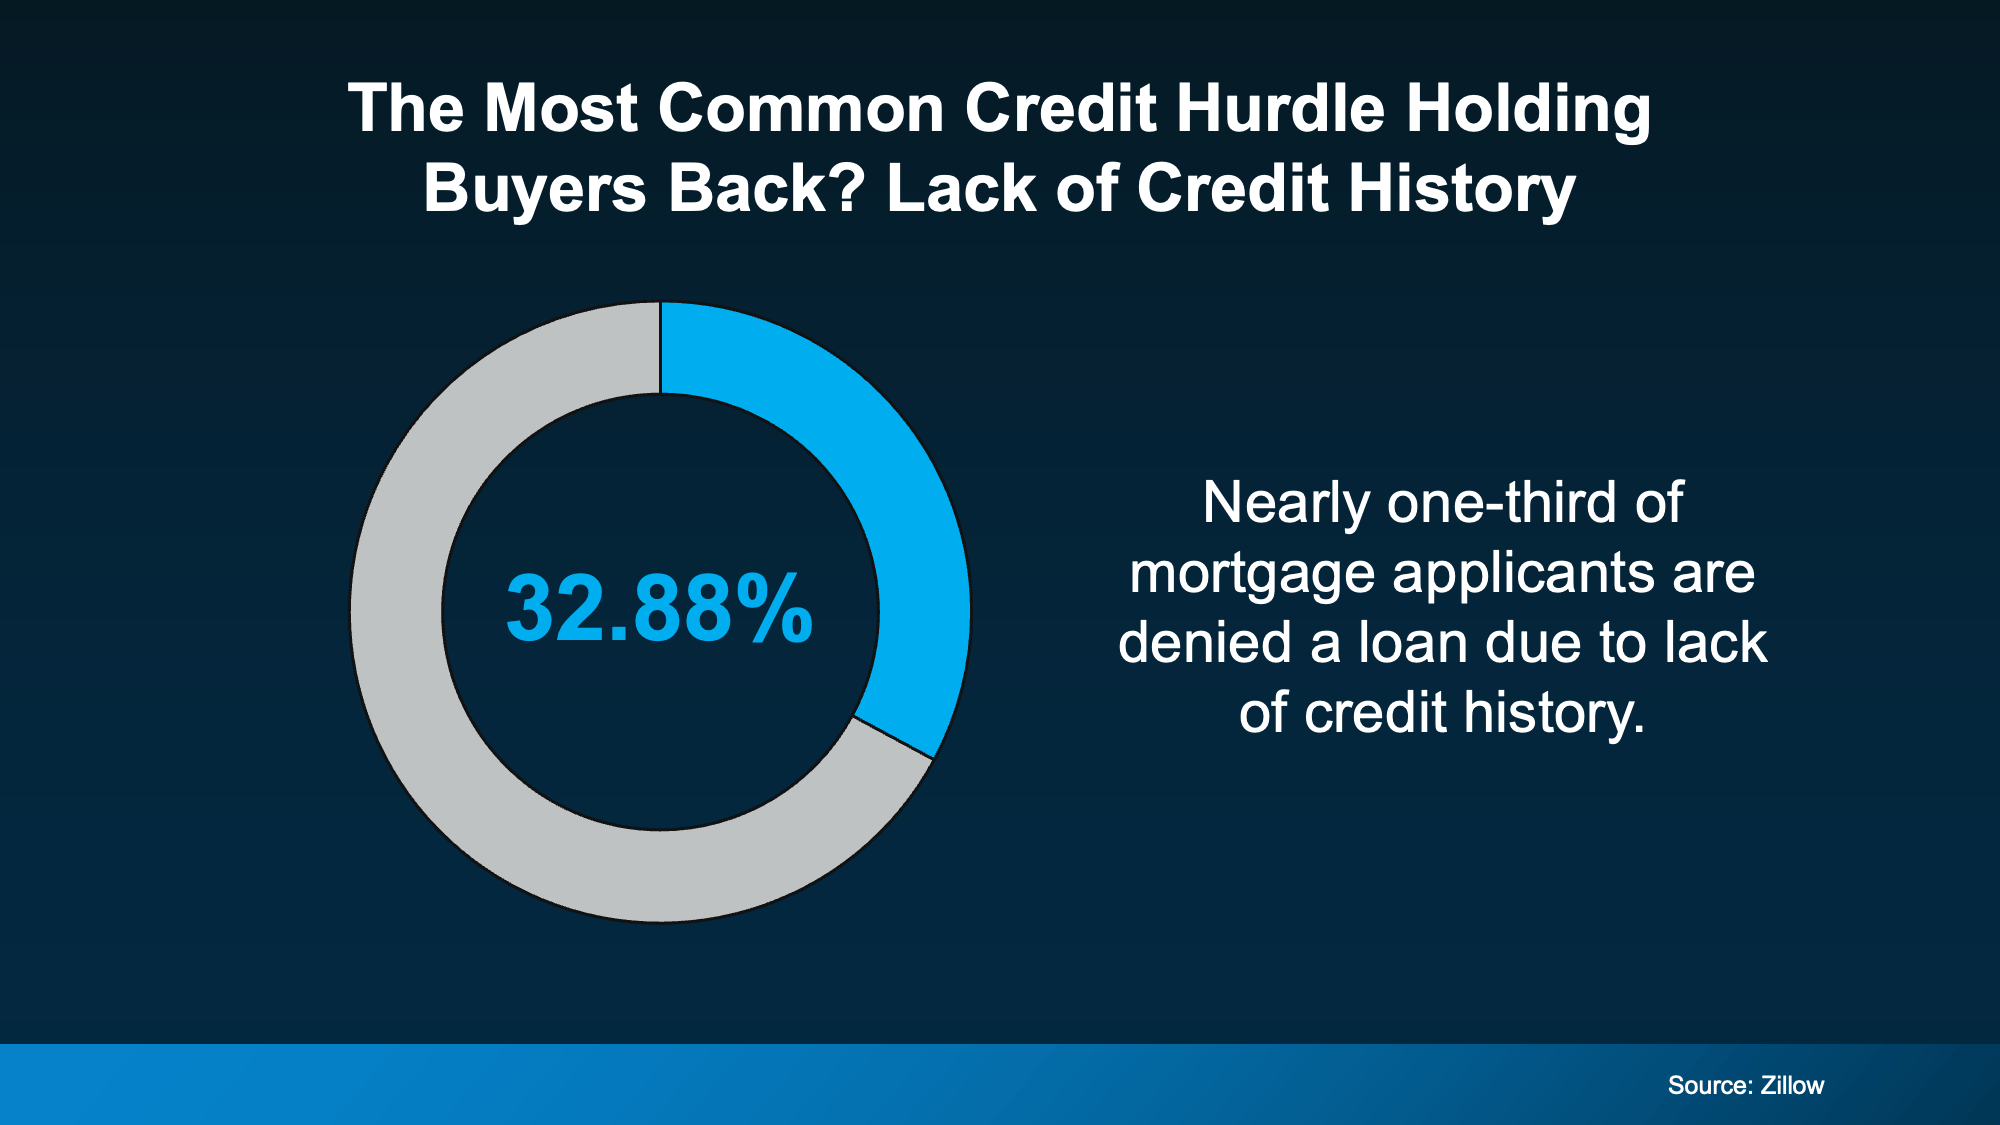
You’re not alone in feeling frustrated. According to Zillow, nearly one third of mortgage applicants (32.88%) are denied because they don’t have enough credit history, not because they missed payments or have too much debt. They simply don’t have enough credit history for lenders to approve them.
It’s one of the biggest challenges potential homebuyers face. Here’s how Zillow explains it:
““Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
”
The good news is that things are changing, giving you a new opportunity to build credit and work toward homeownership.
The Good News: Credit Is Getting Broader
As Michael Sherman, General Manager and Senior Vice President at Zillow Rentals, explains:
““Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”
”
Here’s what Sherman means. New credit models are starting to factor in on time rent and some utility payments, helping renters get credit for the bills they’re already paying every month.
VantageScore has introduced a new credit model approved for use by the Federal Housing Finance Agency (FHFA). This change could make a big difference for renters like you who are working toward buying a home.
A recent study by VantageScore found that nearly 4 million U.S. renters could qualify for a mortgage if their on time rent payments were included in their credit history. It doesn’t mean everyone will automatically qualify, but it could give many renters a new opportunity to become homeowners.
Here’s the thing, though. You still need to take the next step to make it happen.
Counting Rental Payment History Is Not Automatic
You have more ways to build your credit now, but you need to take action. Your rent won’t automatically count, so make sure your payments are being reported. The sooner you start, the better prepared you’ll be when you’re ready to buy a home.
Here are a few simple ways to get started, based on tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:
Ask your landlord or property manager if your rent payments are being reported to credit bureaus. If not, see if you can sign up.
If your landlord doesn’t offer rent reporting, look into available services. Check the fees and which credit bureaus receive your payment history.
Review your credit reports for mistakes. Fixing errors can help improve your credit profile. The CFPB has a step by step guide to help you correct them.
Build good credit habits by paying bills on time, keeping credit card balances low, and avoiding too many new credit applications at once.
Keep your existing credit accounts open, even if you’ve paid them off or rarely use them.
Strengthen your credit history by considering a secured credit card or becoming an authorized user on someone else’s account. This can help you build credit beyond your rent payments.
These steps may take a little time and effort, but they could pay off by helping you build a stronger credit history.
Keep in mind that not all lenders use the same credit scoring model, and more changes are coming. The sooner you start getting credit for the payments you already make, the better.
Even if buying a home isn’t in your immediate plans, talking to a lender is a great first step. They can help you create a plan and figure out what you need to do to get ready to apply for a mortgage when the time comes.
Bottom Line
Credit rules are changing, but you still need to take action. Make sure you’re getting credit for the payments you already make. The sooner you start, the better prepared you’ll be for homeownership.
Want to see where you stand? Talking to a loan officer is free and could help you discover that you’re closer to owning a home than you think.