If you’ve been keeping an eye on mortgage rates, you might be feeling a little discouraged. Rates climbed above 7% this year, leading many buyers to put their plans on hold and wait for rates to come down.
But mortgage rates are only part of the picture. When buying a home, you usually have one of two advantages: lower rates or more negotiating power. It’s rare to have both at once. Right now, buyers have more negotiating power than they may realize.
Why Low Rates and Leverage Don’t Usually Show Up Together
Think back to 2020 and 2021. Mortgage rates were around 3%, bringing plenty of buyers into the market. While those low rates were appealing, there was a downside. You were competing with many other buyers, and there simply weren’t enough homes available to meet the demand.
That’s why homes often received multiple offers, buyers went above asking price, and some even waived inspections just to compete. Sellers had the upper hand. Jake Krimmel, Senior Economist at Realtor.com, explains just how much the market favored sellers:
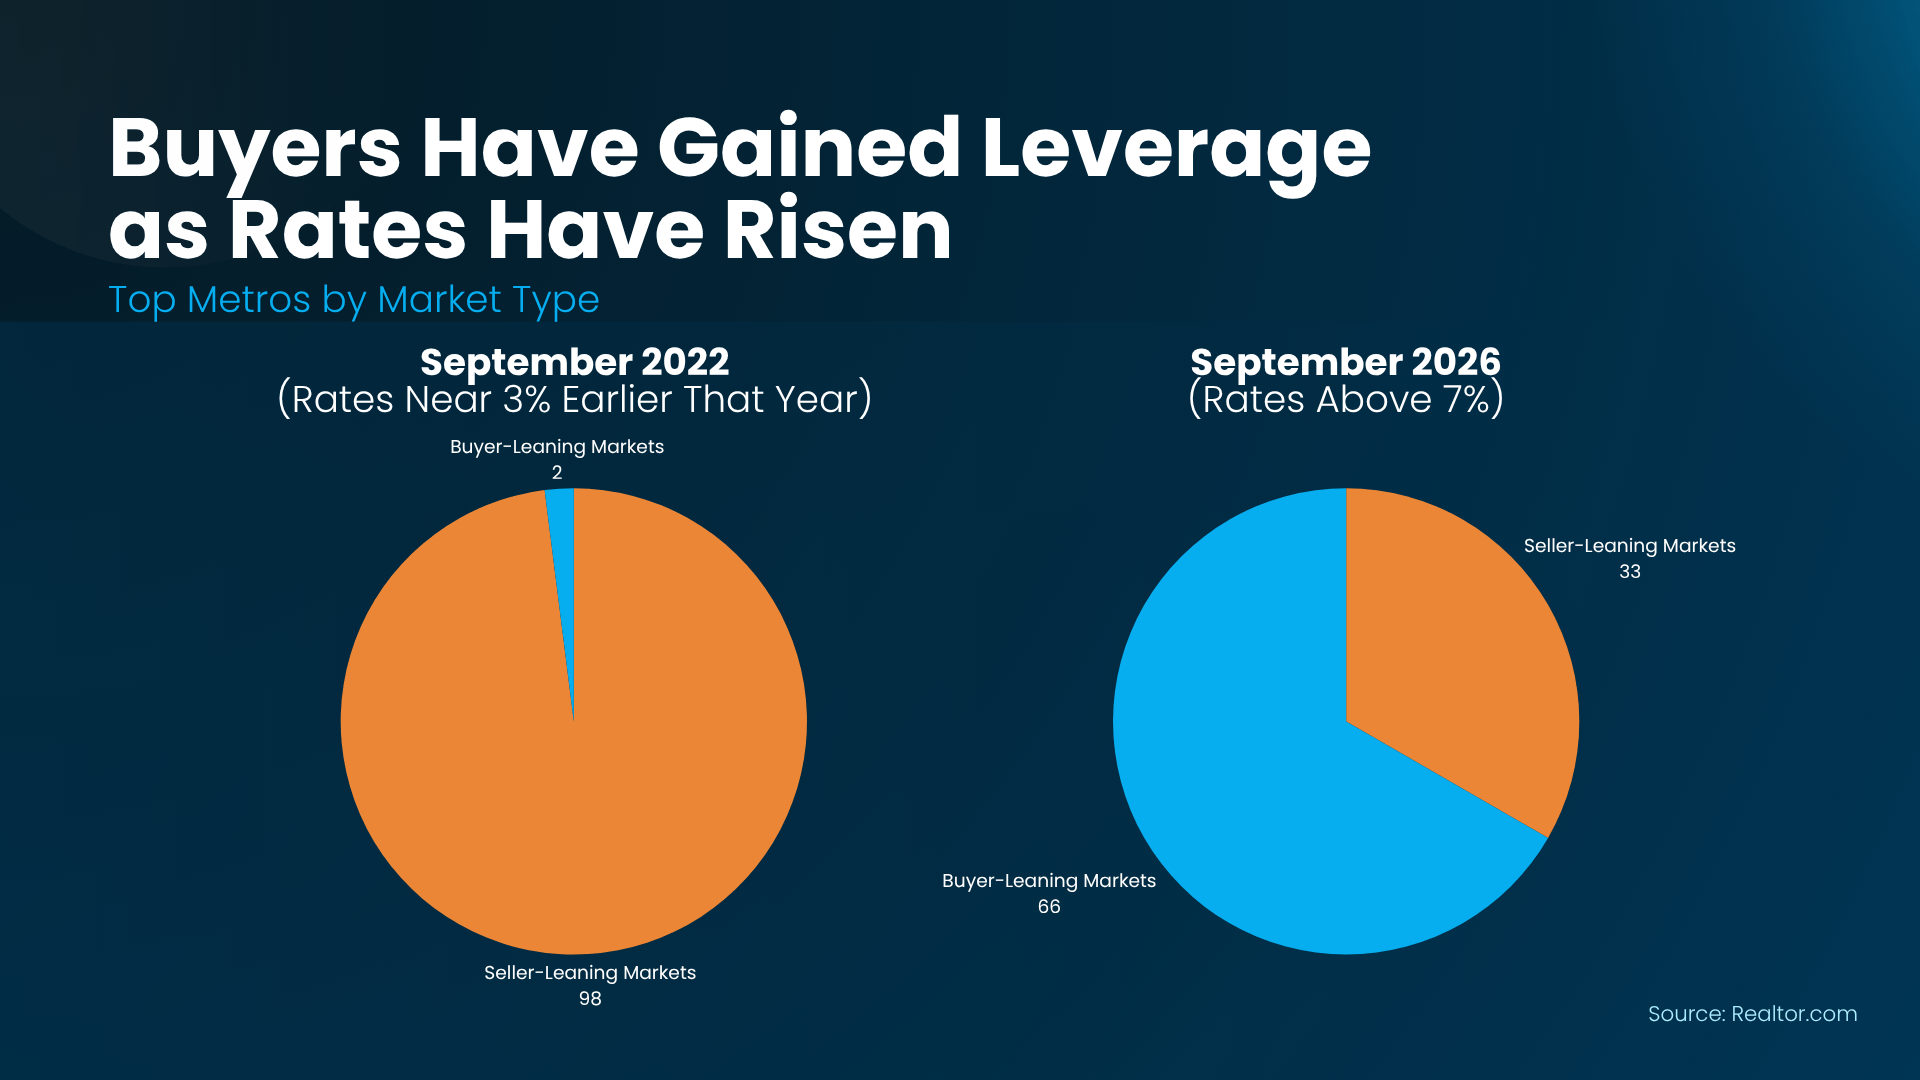
““Seller’s markets peaked at 98 of 100 metros in spring 2022 after two years of mortgage rates near 3%.”
”
Then, rates started climbing in the second half of 2022, causing buyer activity to slow and more homes to hit the market. Gradually, the balance began shifting from sellers to buyers. Now, that shift has officially happened.
A recent Realtor.com report found that about two-thirds (66%) of the top 100 metro areas now favor buyers (see graph below):
And while lower mortgage rates would certainly be nice, having more negotiating power in today’s market comes with some real advantages too.
What Your Leverage Looks Like Right Now
There are more homes on the market now than we’ve seen in years. With more choices available, sellers have to put in more effort to attract buyers and get their homes sold. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:
“Whatever it is, the way you tell your story online can make all the difference.”
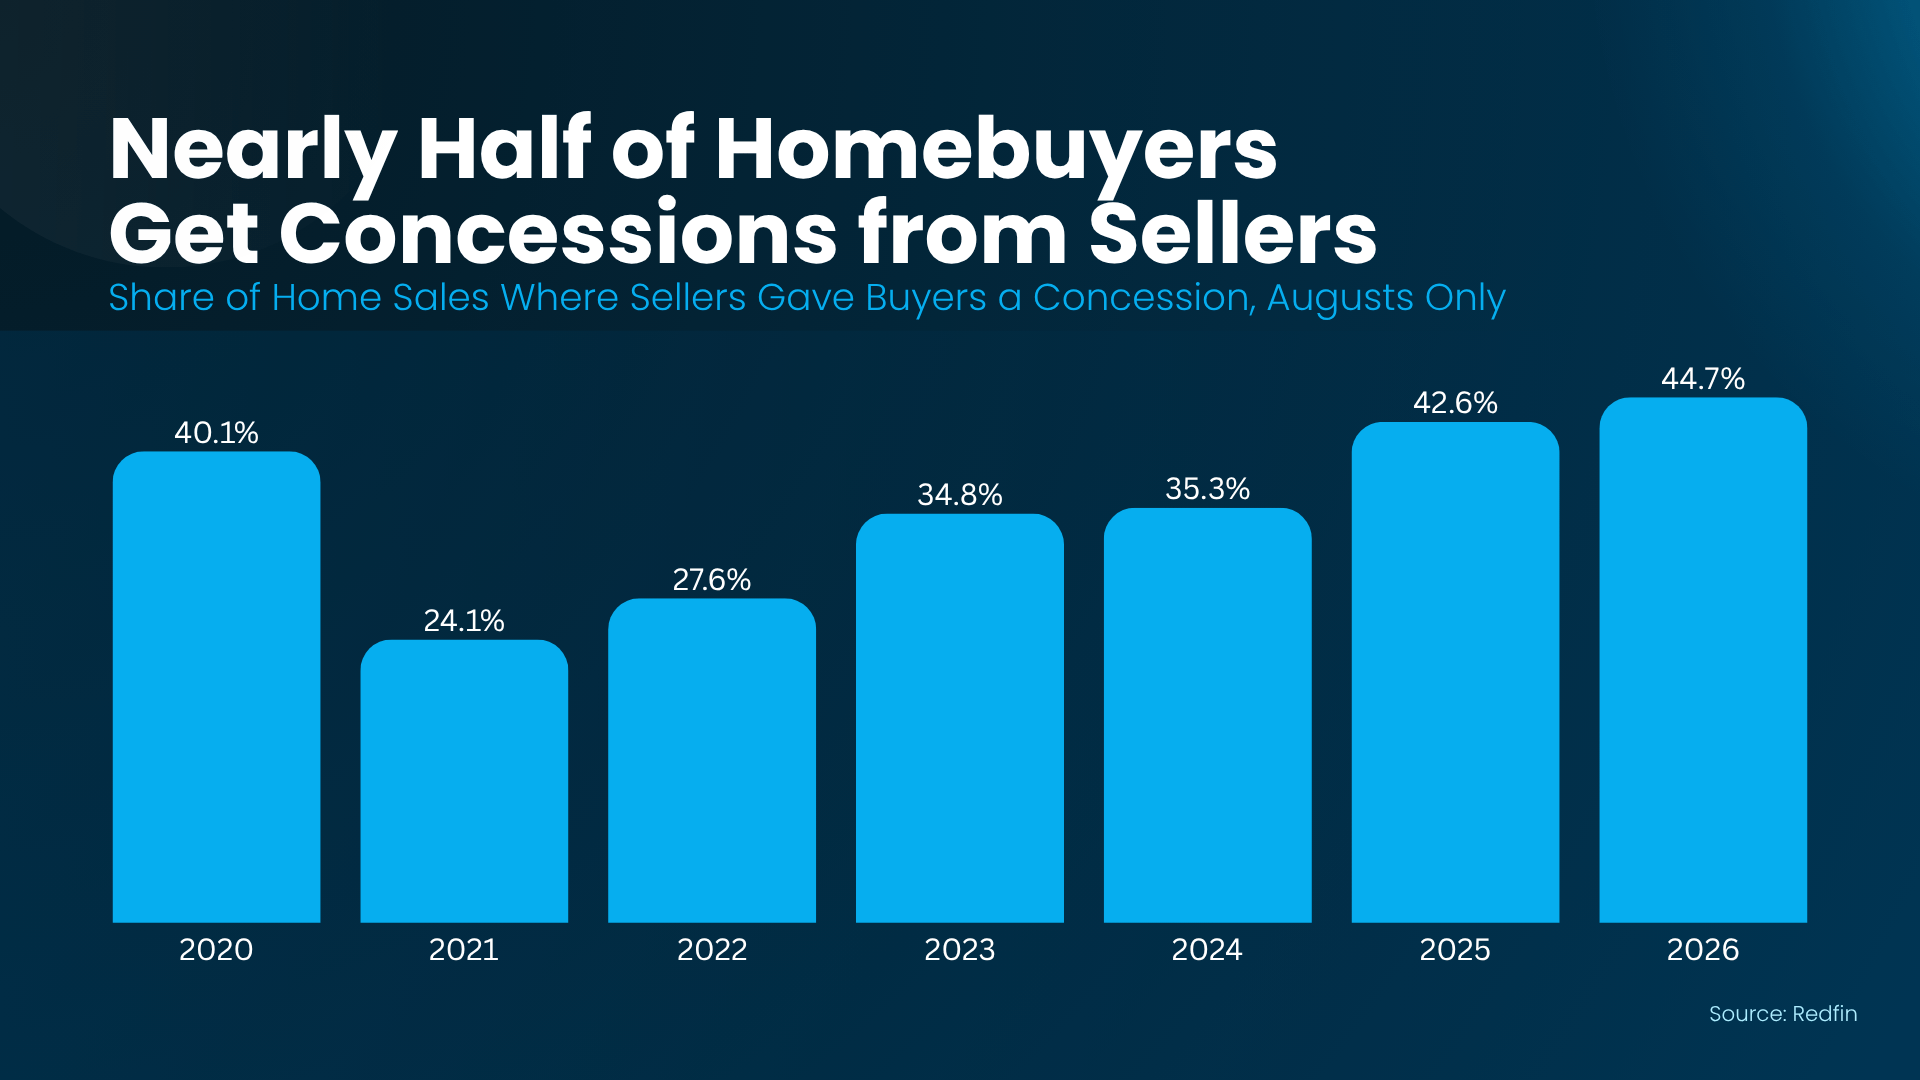
You can see this shift in the deals buyers are getting today. According to Redfin, nearly half of buyers are receiving seller concessions, such as help with closing costs, repair credits, or even money to lower their mortgage rate (see graph below):
So when you find a home you love, even if the mortgage rate isn’t ideal, you still have options. You can negotiate a lower price or ask the seller to help buy down your rate. These strategies could make today’s rates a little easier to manage.
Why Waiting for Lower Rates Could Backfire
And if you’re thinking about waiting until mortgage rates drop, here’s something to keep in mind. Experts at Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo don’t expect rates to come down much through 2027 (see graph below):
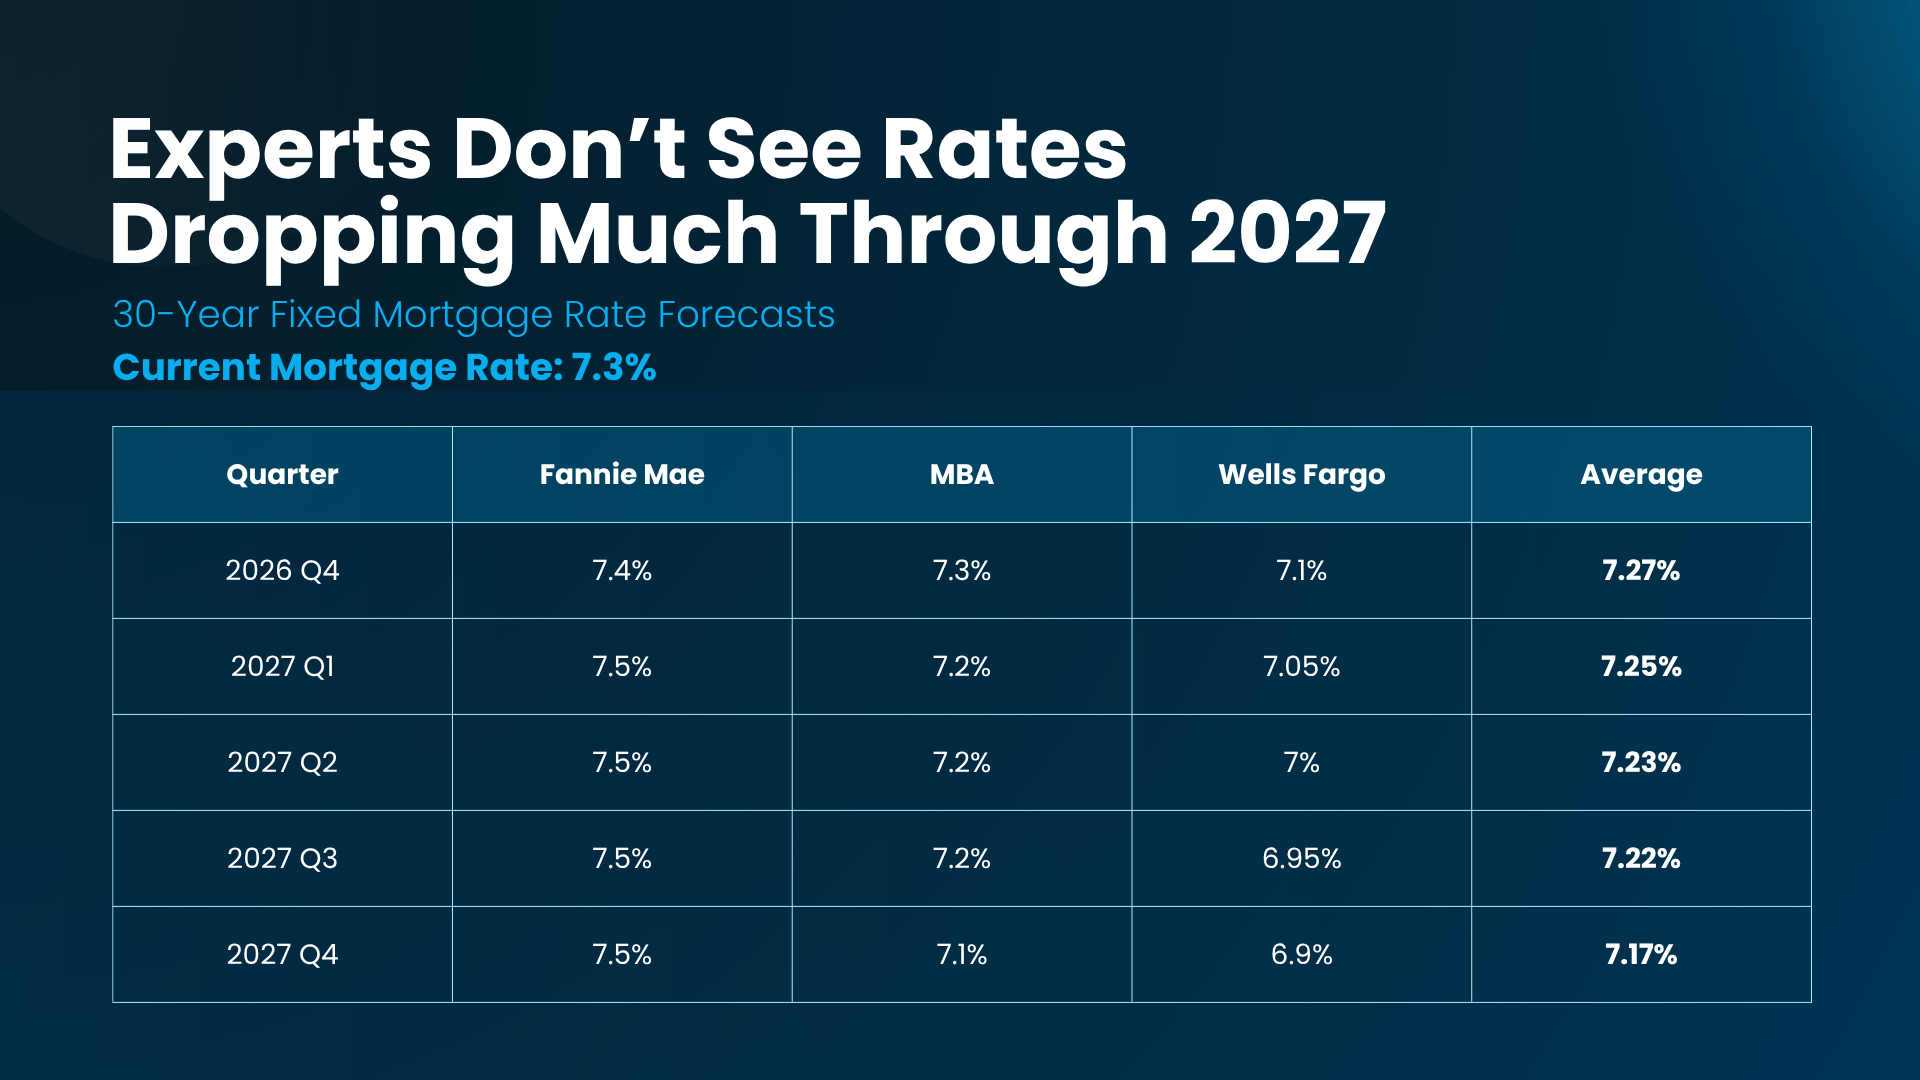
Here’s what it really comes down to. If mortgage rates dropped significantly, more buyers would likely jump back into the market. That means more competition, fewer seller concessions, and sellers gaining the upper hand again.
Waiting means weighing your options. You might get a lower mortgage rate later, but you could also lose the negotiating power and advantages buyers have in today’s market.
That doesn’t mean you need to buy a home right away. The most important thing is making sure the numbers fit your budget. But if you have a good reason to move, the negotiating power buyers have today could help make buying more affordable, even with current mortgage rates.
Bottom Line
It’s not often that buyers get both low mortgage rates and strong negotiating power. Right now, though, you have the advantage when it comes to negotiating.
Let’s explore homes where sellers may be willing to help with closing costs or lower your mortgage rate, so we can see how to make the most of today’s market and your budget.